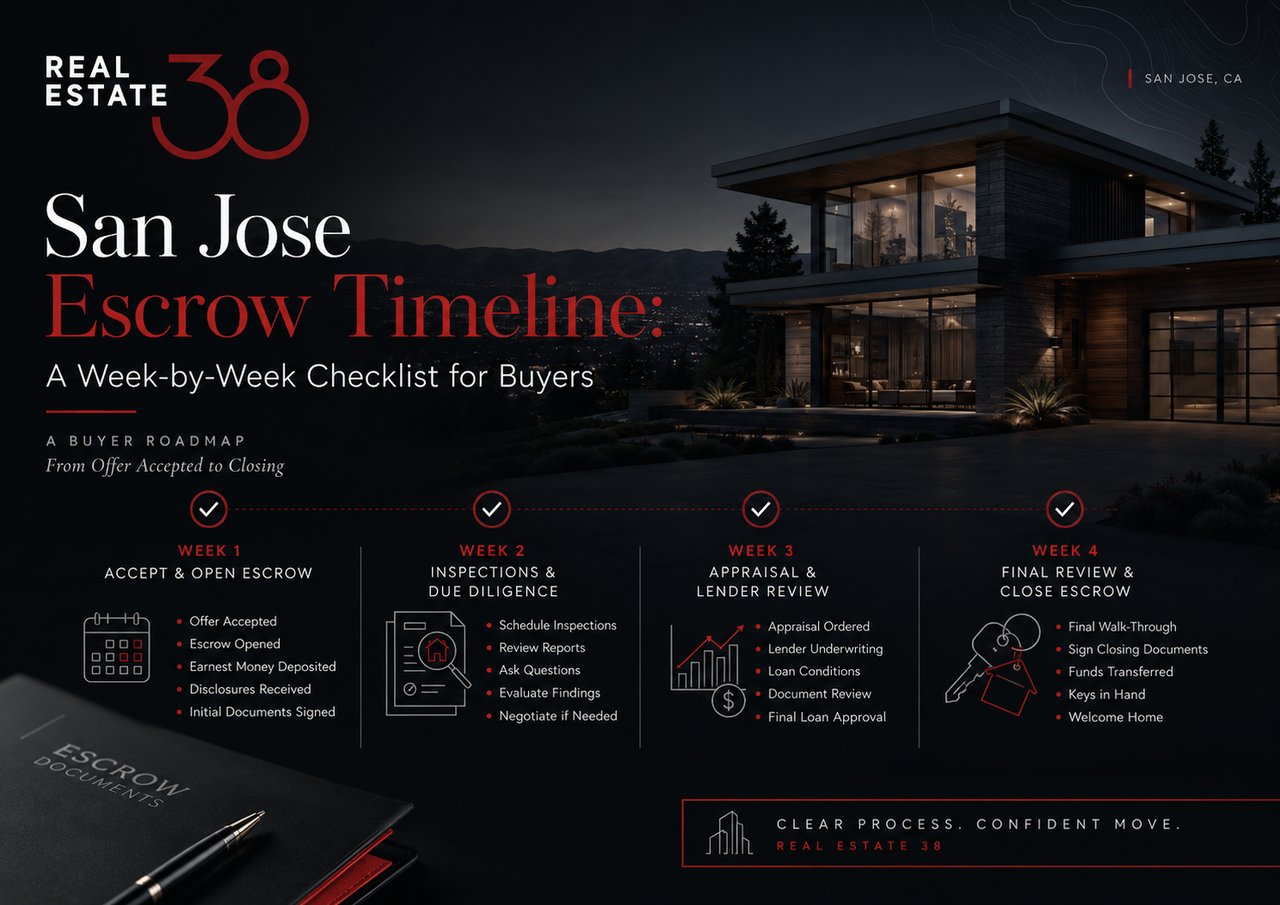
San Jose Escrow Timeline: A Week-by-Week Checklist for Buyers
Home Buyer
Home Buyer
Getting your offer accepted is exciting, but it is not the finish line.
In many ways, that is when the real work begins.
Once a San Jose buyer gets into contract, escrow starts moving quickly. There are deposits to make, inspections to schedule, disclosures to review, loan documents to complete, appraisal steps to track, contingencies to manage, and closing deadlines that cannot be ignored.
That does not mean escrow needs to feel overwhelming.
When you understand the timeline and have the right team coordinating the process, escrow becomes much more manageable. My job is to help buyers know what is happening, what decisions need to be made, what deadlines matter, and where they need to be protected.
This guide walks through the typical San Jose escrow timeline week by week so you know what to expect after your offer is accepted.
For a bigger picture view of the full buying process, I also recommend reading our San Jose Home Buying Process Guide here:
https://re38.com/san-jose-home-buying-process-guide
Escrow is the neutral process that happens between offer acceptance and closing.
After a buyer and seller agree on the purchase contract, escrow helps manage the money, documents, title transfer, lender paperwork, and closing instructions. Escrow does not represent the buyer or the seller. Their role is to follow the contract and help coordinate the closing process.
In simple terms, escrow is where the transaction gets organized, verified, funded, and completed.
For buyers, escrow usually includes:
The exact timeline depends on the purchase contract, loan type, property type, seller expectations, buyer strategy, and how quickly each party performs.
A financed buyer, cash buyer, condo buyer, townhouse buyer, and single-family home buyer may all have different escrow risks.
That is why I never treat escrow like a generic checklist. I treat it like a contract timeline that needs to be actively managed.
The first 24 to 72 hours after offer acceptance are extremely important.
This is when escrow is opened, the signed contract gets distributed, the buyer’s lender gets moving, and the buyer needs to prepare the earnest money deposit.
In San Jose, buyers often move fast because contract timelines can be tight. Even when the escrow period is 21, 25, or 30 days, the first few days set the tone for the entire transaction.
Right after acceptance, we usually focus on:
One of the first things I do with my buyers is map out the contract deadlines.
The biggest mistake buyers make is assuming escrow is just paperwork. It is not. Escrow is a series of deadlines, decisions, and risk-management steps.
The first week is usually the busiest part of escrow.
This is when we confirm the contract, open escrow, handle the earnest money deposit, review disclosures, schedule inspections, communicate with the lender, and start identifying any major concerns early.
Once the offer is accepted, escrow is opened with the escrow company identified in the contract or agreed to by the parties.
The escrow officer will usually send introductory paperwork, wire instructions, estimated closing statements, and next-step instructions.
One very important warning: buyers should always verify wire instructions before sending money.
Wire fraud is real. I always tell buyers to confirm instructions directly with escrow using a trusted phone number, not just by replying to an email.
The earnest money deposit is the buyer’s good-faith deposit. It shows the seller that the buyer is serious and committed to performing under the contract.
The exact deposit amount and timing are controlled by the signed purchase contract. In many California transactions, the deposit is due within a short period after acceptance, often within a few business days, but buyers should never assume. We always check the contract.
This deposit matters because it can be at risk if a buyer removes contingencies and later does not perform.
Before sending the deposit, buyers should understand:
The goal is not to scare buyers. The goal is to make sure they understand what they are committing to.
The purchase contract is the roadmap for the escrow timeline.
During the first week, I want buyers to understand the major terms, including:
This is where a strong agent matters. Buyers should know what they signed, what protections they have, what dates matter, and what decisions are coming.
If the buyer has an inspection contingency or property investigation period, the first week is when we schedule inspections quickly.
For a San Jose single-family home, we may look at:
For a condo or townhouse, we may also review:
Condos and townhomes often have a different risk profile than single-family homes.
A beautifully updated unit can still have HOA concerns that affect financing, insurance, monthly cost, resale value, or buyer confidence.
In San Jose, disclosures are a major part of buyer protection.
The seller disclosures, inspection reports, title documents, HOA documents, and supplemental disclosures can reveal issues that are not obvious during a showing.
I help buyers review disclosures for red flags such as:
Buyers do not need to panic when they see issues. Almost every property has something.
The important question is whether the issue is normal, manageable, negotiable, or serious enough to change the buyer’s decision.
By the second week, the buyer should be deep into loan processing, inspection review, disclosure questions, insurance quotes, and appraisal timing.
This is also when buyer contingency deadlines can start approaching quickly.
For financed buyers, the lender is a huge part of the escrow timeline.
Even if the buyer was pre-approved before writing the offer, the lender still needs to process the file for the specific property.
This can include:
A strong lender can make escrow smoother. A weak lender can create stress, missed deadlines, and closing risk.
In a competitive San Jose market, I want lenders who communicate clearly, understand local timelines, respond quickly, and know how to work with listing agents, escrow officers, and underwriters.
If the buyer is using financing, the lender typically orders the appraisal.
The appraisal is the lender’s opinion of value for the property. The lender wants to confirm that the home supports the loan amount.
Timing can vary, but we want the appraisal ordered early and tracked closely.
If the appraisal contingency deadline is approaching, we need to know whether the report is complete, whether there are value concerns, and whether the lender needs anything else.
A low appraisal does not automatically kill the deal, but it does create a decision point.
If the appraisal comes in below the purchase price, the buyer may need to evaluate options such as:
The right strategy depends on the contract, the appraisal gap, the buyer’s cash position, the property, and the seller’s motivation.
This is one reason buyers should not waive appraisal protection blindly.
In some situations, waiving or shortening an appraisal contingency can help win an offer. In other situations, it can expose the buyer to real financial risk.
One of the most important parts of escrow is understanding how deadlines overlap.
A buyer may be dealing with:
These are not random dates. They determine when a buyer can investigate, renegotiate, cancel, move forward, or remove protections.
For example, a buyer may be comfortable with the inspection results but still waiting for the appraisal.
Or the appraisal may be fine, but the lender has not issued final loan approval.
Or the property condition may be acceptable, but the HOA documents raise concerns.
That is why I do not look at each contingency in isolation. I look at the entire escrow timeline and ask:
This is where coordination matters.
Insurance is another item buyers should start early.
In some transactions, insurance is simple. In others, especially with older homes, hillside properties, higher fire-risk areas, prior claims, roof concerns, or certain condo and townhouse situations, insurance can become a real closing issue.
Buyers should not wait until the final week to shop insurance.
Insurance can affect:
For condos and townhomes, the HOA master insurance policy may also matter. The lender may need to review coverage, deductibles, and policy details before approving the loan.
If inspections or disclosures reveal concerns, the buyer may have a negotiation window depending on the contract terms and contingencies.
Repair requests can include:
In San Jose, the right approach depends on the market and the property.
If the buyer negotiated hard to win the home, we need to be strategic. If the seller had limited interest or the issue is material, there may be more room to negotiate.
I do not recommend sending a long list of minor cosmetic requests unless there is a clear strategy.
The best repair negotiations focus on meaningful issues that affect safety, systems, insurability, financing, cost, or buyer confidence.
By the third week, many buyers are approaching major decision points.
This is when we often need to decide whether to remove contingencies, continue negotiating, request extensions, or cancel if the buyer is still protected and the risk is too high.
Removing contingencies is a serious step.
Once a buyer removes contingencies, their protections may be reduced, and their earnest money deposit may be more exposed if they later fail to close for a reason that is no longer protected.
This does not mean buyers should be afraid to remove contingencies.
It means they should remove them only when they have enough information.
Before a buyer removes contingencies, I want to know:
Buyers should not remove contingencies just because someone says, “It is time.”
They should remove contingencies because the right information has been reviewed and the buyer is making an informed decision.
After contingencies are removed, escrow usually shifts from investigation mode to closing mode.
The buyer is still working with the lender, escrow, title, insurance, and their agent, but the focus becomes completion.
At this stage, we are usually tracking:
This is also when buyers should avoid making major financial changes.
I remind buyers not to open new credit, finance furniture, change jobs, move large amounts of money without lender guidance, or make financial decisions that could affect loan approval.
Final loan approval means the lender has reviewed the buyer, the property, the appraisal, title, insurance, and loan conditions.
Clear to close means the lender is ready for closing documents to be prepared and signed, assuming all final steps are completed properly.
This is one of the reasons communication is so important.
A buyer can feel like they are almost done, but one missing condition can delay closing.
The lender, agent, escrow officer, and buyer all need to stay aligned so there are no surprises at the end.
The final week of escrow is where everything comes together.
This stage feels exciting, but there are still important details to manage.
For financed buyers, escrow will schedule a signing appointment once loan documents are ready.
The buyer will review and sign a large package of loan and closing documents. This may happen at the escrow office, with a notary, or through another approved signing process.
Signing does not mean the buyer owns the home yet.
It means the closing documents have been signed and the transaction is moving toward funding and recording.
Before closing, the buyer must deposit the remaining funds needed to close.
This can include:
Again, buyers should verify wire instructions directly with escrow before sending funds.
The final walkthrough usually happens shortly before closing.
This is not a new inspection. It is the buyer’s opportunity to confirm the property is in the expected condition, agreed-upon repairs are completed if applicable, included items remain, and no major new issues have appeared since the buyer’s last visit.
During the final walkthrough, we typically check:
If something is wrong, we address it before closing when possible.
In California, the buyer typically becomes the owner when the deed records with the county.
After recording is confirmed, escrow notifies the parties, and keys can be released based on the contract terms.
Sometimes keys are available right after recording. Sometimes possession terms are different if the contract includes a seller rent-back, delayed possession, or another arrangement.
That is why we confirm possession terms early, not at the last minute.
Most escrow delays are preventable when everyone communicates early.
Common delays include:
In San Jose, condos and townhomes can also involve additional HOA review, insurance questions, litigation concerns, rental restriction questions, and lender requirements.
Single-family homes may have different risks, including inspections, permits, drainage, foundation, roof, sewer, additions, and older systems.
The key is not to assume every property has the same escrow path. The property type matters.
Cash buyers and financed buyers can have very different escrow timelines.
A cash buyer may be able to close faster because there is no lender underwriting or lender appraisal requirement.
However, cash buyers still need to review title, disclosures, inspections, escrow documents, HOA documents if applicable, and final funds.
A financed buyer usually has more moving parts because the lender needs to approve both the buyer and the property.
A financed escrow may include:
A cash escrow may be simpler, but simple does not mean risk-free.
Cash buyers still need to protect themselves through investigation, title review, document review, and clear communication.
The best way to avoid escrow problems is to build the timeline immediately after acceptance.
Here is what I want buyers to do:
Escrow rewards buyers who are organized.
It punishes buyers who disappear, delay, or assume everything is being handled automatically.
At Real Estate 38, we help buyers manage escrow by staying ahead of the timeline instead of reacting at the last minute.
When I represent a San Jose buyer, I help coordinate:
My goal is not just to help buyers get into contract.
My goal is to help them close with confidence.
A strong offer matters, but a strong escrow process matters just as much.
If you are still preparing to buy, you can also learn more about our San Jose home buying approach here:
Escrow can feel like a lot because there are many moving pieces.
But when the buyer understands the timeline, knows the deadlines, works with a strong lender, reviews documents carefully, and has an agent coordinating the process, escrow becomes much easier to manage.
The biggest thing I want San Jose buyers to understand is this:
Do not wait until after your offer is accepted to learn how escrow works.
Before you write an offer, you should understand the deposit, contingencies, inspection timeline, appraisal risk, loan deadlines, closing process, and what could put your money at risk.
And if you are already in contract, do not guess your way through escrow. Get clear on your deadlines immediately.
If you are preparing to buy in San Jose or you just got into contract, contact me before you make your next move:
I can help you understand the escrow timeline, protect your deposit, stay ahead of deadlines, and close with confidence.
For more guidance, learn about buying a home in San Jose, explore current homes for sale, compare San Jose neighborhoods, or meet Zaid Hanna and the Real Estate 38 team.
Zaid Hanna
408-515-1613
www.re38.com
Stay up to date on the latest real estate trends.
October 21, 2026
October 20, 2026
October 19, 2026
October 14, 2026
October 12, 2026
October 9, 2026
You’ve got questions, and we can’t wait to answer them.