How Much Do I Need for a Down Payment to Buy a Home in San Jose?
Home Loans, Mortgage Rates & Affordability Guide
Home Loans, Mortgage Rates & Affordability Guide
By Zaid Hanna, Broker, Real Estate 38 · CA DRE #01421581 · Published December 18, 2025
One of the biggest misconceptions I hear from buyers is:
“I need 20% down to buy a home in San Jose.”
That belief stops many qualified buyers from even starting the conversation — especially in a high-priced market like ours.
The reality is: there is no single “required” down payment amount.
Your ideal down payment depends on your goals, loan type, income structure, monthly comfort, and long-term strategy.
This guide breaks down the real down payment options available in San Jose and explains when putting less down can actually make sense.
For a full overview of financing options, start here:
👉 https://re38.com/san-jose-home-loan-mortgage-guide
Twenty percent down helps you avoid PMI, but it is not required for most conventional loans — even in San Jose.
What matters more is:
affordability
monthly payment comfort
loan structure
long-term plan
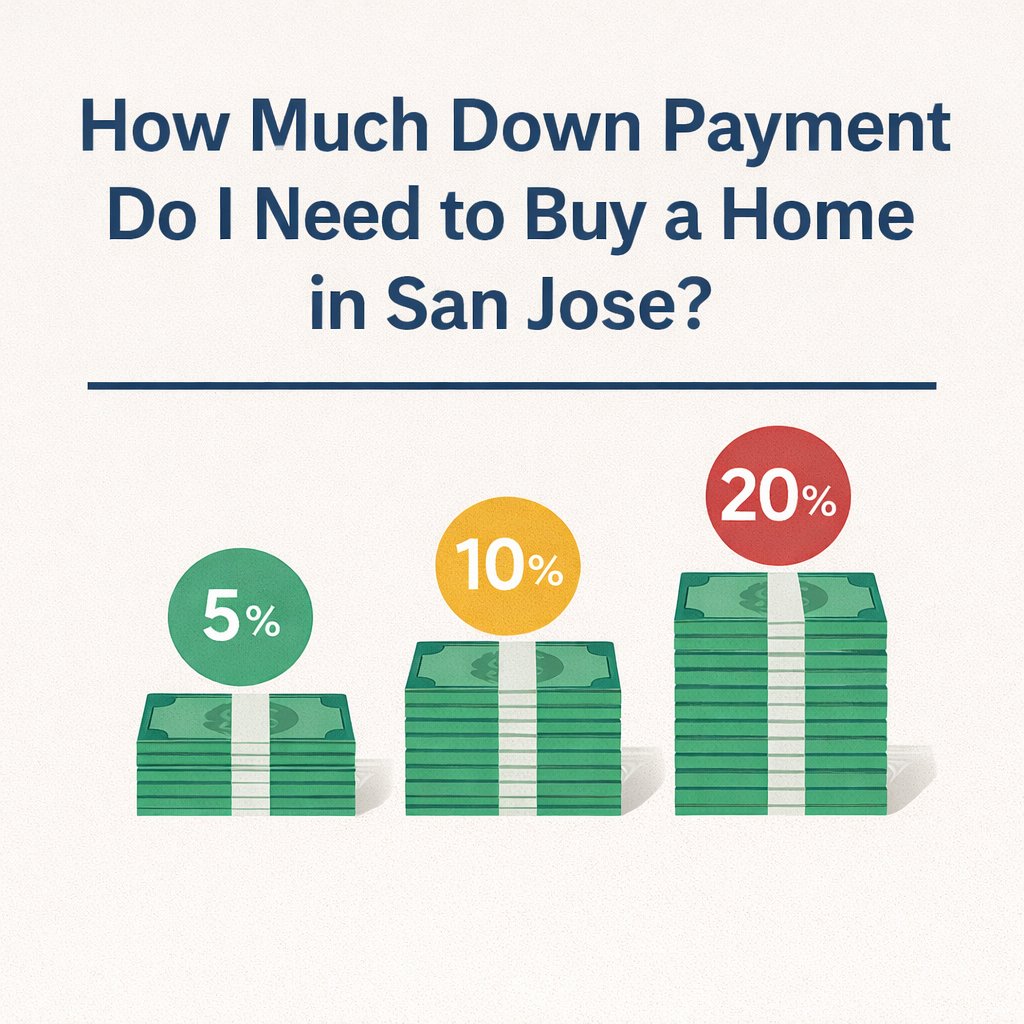
Here’s how most buyers structure their down payments:
First-time buyers
Strong credit profiles
Conventional loans
PMI required
Best for buyers who want to enter the market sooner.
Very common in San Jose
Balanced approach
Lower PMI than 5%
Keeps more cash available
Often ideal for tech buyers.
Reduces or eliminates PMI
Lower monthly payment
Stronger offer profile
Preferred by move-up buyers.
No PMI
Lowest monthly payment
Best for long-term holds
Common for equity-rich buyers or those using RSUs.
Let’s translate percentages into real numbers.
5% down = $60,000
10% down = $120,000
20% down = $240,000
5% down = $80,000
10% down = $160,000
20% down = $320,000
Seeing it this way helps buyers realize that waiting to save 20% can delay ownership by years.
PMI (Private Mortgage Insurance):
protects the lender
applies when down payment is under 20%
is not permanent
In many cases:
PMI costs less than expected
PMI can be removed once you reach 20% equity
appreciation in San Jose can accelerate removal
Paying PMI for a few years is often cheaper than waiting on the sidelines.
Putting less down can be smart if:
you have strong income
your monthly payment is comfortable
you want to keep cash for:
reserves
investments
remodeling
emergencies
Many San Jose buyers prefer liquidity over tying up all their cash in a down payment.
A larger down payment may be better if:
you want the lowest possible payment
you’re rate-sensitive
you’re buying long-term
you want to avoid PMI
you’re using proceeds from a sale
There’s no “right” answer — only what fits your strategy.
In San Jose, many purchases fall into jumbo loan territory.
Jumbo loans often:
require higher down payments (10–20%)
have stricter reserve requirements
offer competitive rates for strong borrowers
This is why structuring your down payment with the right lender is critical.
Remember, you also need funds for:
closing costs
inspections
appraisal
reserves
A smart plan balances:
down payment
monthly payment
cash reserves
For the full buying roadmap, review:
👉 https://re38.com/san-jose-home-buying-process-guide
Instead of guessing how much you need, let’s look at your numbers together.
We’ll review:
income and bonuses/RSUs
credit profile
loan options
monthly comfort level
down payment scenarios
what homes fit your budget
👉 Reach out here:
https://re38.com/contact
A quick conversation can help you understand your real options and create a plan that works — without pressure.
No. Twenty percent avoids mortgage insurance on a conventional loan, but it isn't required. At the October 2026 median house price of $1,615,000, 20% would be $323,000. Many buyers put down less, depending on the loan, income and how much cash they want to keep.
It depends on the loan. FHA starts at 3.5%, some conventional programs start at 3%, and VA can be zero with full entitlement. Price matters here. Loans above the 2026 Santa Clara County limit of $1,249,125 are jumbo, and jumbo lenders often want more down. See my San Jose home loan guide.
According to the CFPB, you can ask your servicer to cancel it when your balance reaches 80% of the home's original value, if you meet its requirements. It generally must end when the balance is scheduled to reach 78%, as long as you're current on your payments.
Often, yes, but rules vary by loan type and lender. You'll usually need a signed gift letter and a paper trail showing the funds moving from the donor to you. Talk to your lender before the money moves, so the deposit doesn't create a problem during underwriting.
Zaid Hanna
408-515-1613
www.re38.com
Stay up to date on the latest real estate trends.
November 20, 2026
November 18, 2026
November 16, 2026
November 13, 2026
November 11, 2026
November 9, 2026
You’ve got questions, and we can’t wait to answer them.